Lars Flores · 25 September 2026
Export Tariffs Prompt Supply Chain Adjustments Among Regional Woodworkers
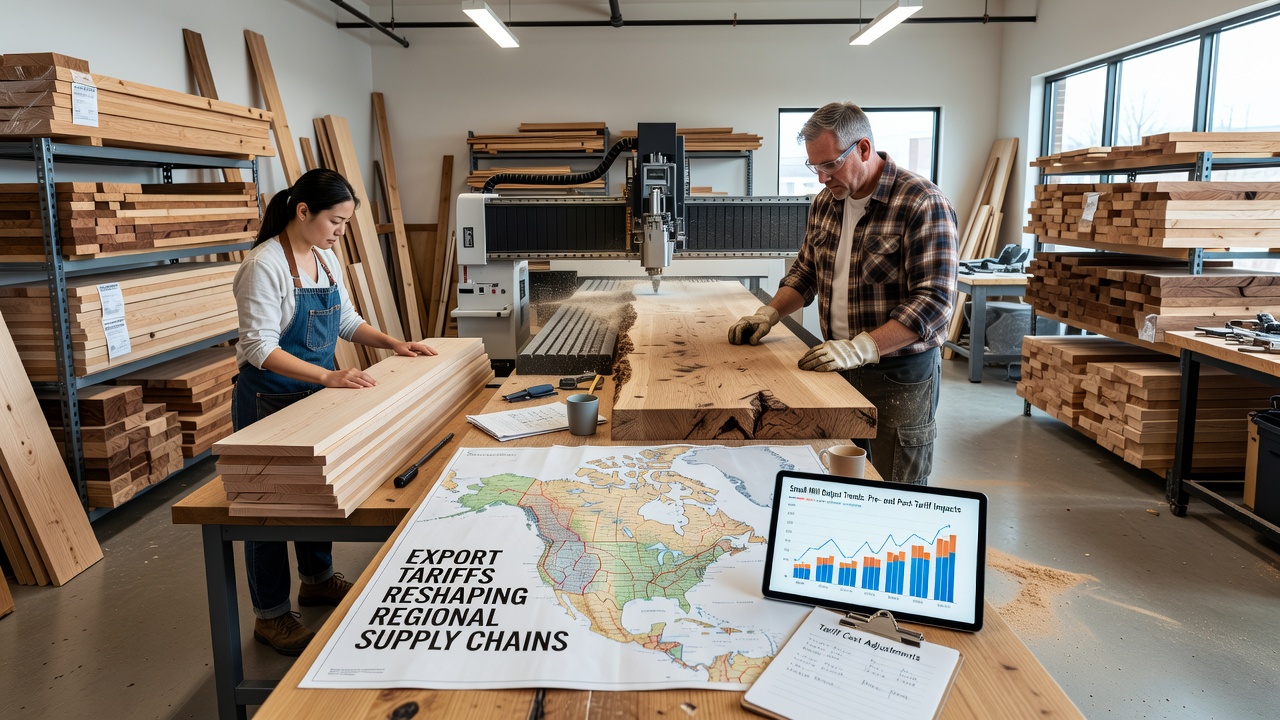
Export tariffs on lumber and raw timber have altered sourcing patterns for regional woodworkers and small mills since early 2025, according to data compiled by the United States International Trade Commission. Mills that once relied on steady imports of specialty hardwoods now face higher costs when those materials cross borders, while domestic log supplies tighten as producers redirect shipments to avoid duties in key markets.
Small operations in the Pacific Northwest and Appalachian regions report shifts in procurement, with some turning to local suppliers that previously served larger facilities. Figures from Natural Resources Canada show a 12 percent drop in softwood exports to the United States during the first half of 2026, prompting mills on both sides of the border to renegotiate contracts and explore alternative species.
Changes in Raw Material Availability
Regional woodworkers who depend on consistent deliveries of maple, oak, and pine now encounter longer lead times and price fluctuations tied directly to tariff schedules. Data indicates that mills processing under 50,000 board feet annually absorb these increases more acutely than larger competitors because they lack volume-based discounts or diversified supplier networks.
Observers note that many small mills have begun sourcing from closer forests to reduce exposure to cross-border fees, although this adjustment requires investments in new equipment calibrated for regional timber grades. One study released by the European Commission Directorate-General for Trade in September 2026 documented similar patterns among European artisans facing duties on North American hardwoods, where workshops adjusted cutting schedules to match irregular domestic log deliveries.
Logistics and Inventory Strategies
Supply chain managers at small mills have implemented staggered ordering systems that combine partial shipments with buffer stocks of kiln-dried lumber. These approaches reduce the risk of sudden tariff spikes yet increase storage expenses, a trade-off documented in industry reports from the Forest Products Association of Canada. Mills that adopted just-in-time models before 2025 now maintain larger on-site inventories to maintain production continuity through tariff review periods.
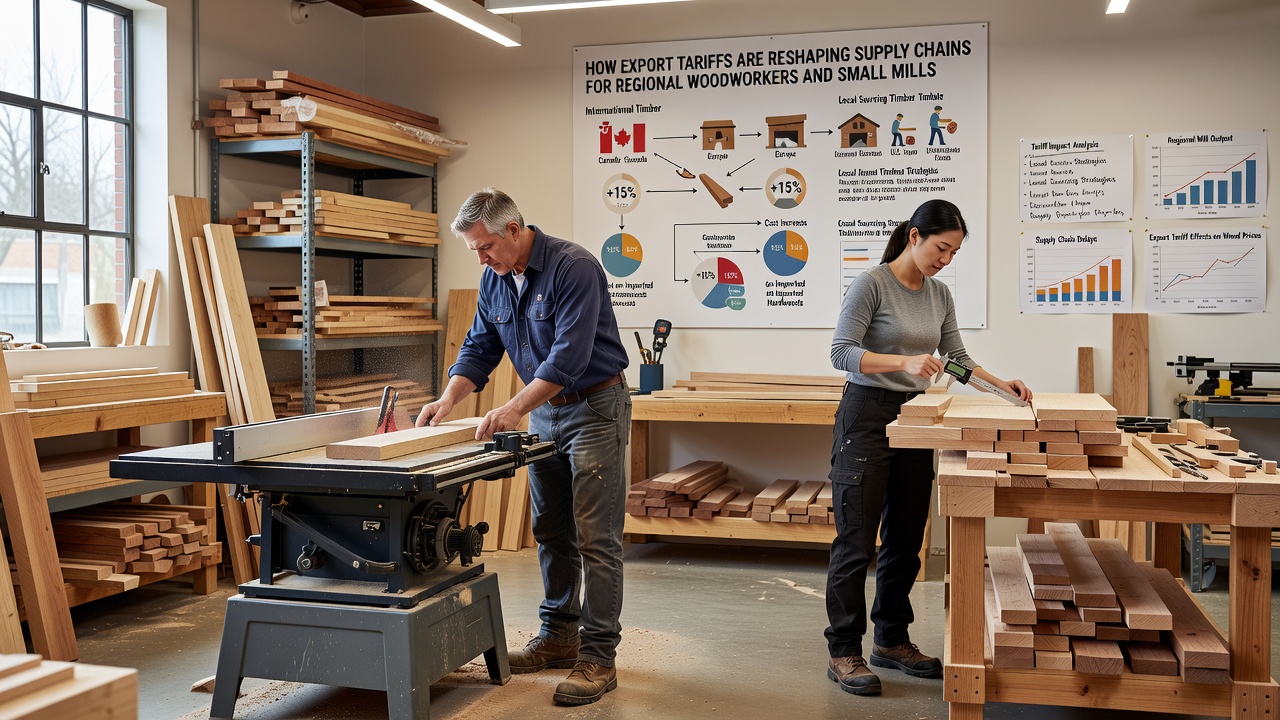
Transportation providers have adjusted routes accordingly, with some carriers offering consolidated loads that combine outputs from multiple small mills to achieve economies previously available only to larger exporters. Researchers at the University of British Columbia's Faculty of Forestry found that these consolidated shipments lowered per-unit logistics costs by an average of 8 percent for participating mills during the second quarter of 2026.
Adaptations in Product Lines
Woodworkers have shifted product emphasis toward items that utilize more readily available local species, reducing reliance on tariff-affected imports. Furniture makers who previously featured imported cherry now incorporate greater volumes of regionally grown ash and poplar, according to production records shared with state forestry offices. Small mills report parallel changes, with several converting portions of their capacity to value-added products such as pre-milled flooring that commands steadier domestic demand.
These transitions require updated training for operators and recalibrated machinery settings, steps that take time and capital. Government assistance programs in several states have provided matching funds for equipment upgrades, although participation rates vary by region and mill size.
Market Responses and Future Outlook
Industry associations track how tariff adjustments influence downstream pricing, with retail outlets noting modest increases in finished wood goods that incorporate previously imported components. Analysts from the Australian Bureau of Agricultural and Resource Economics and Sciences project continued volatility through 2027 unless new trade agreements stabilize raw material flows.
Regional woodworkers continue to monitor policy developments while refining supplier relationships that emphasize proximity and flexibility. Data from multiple agencies shows that mills adopting diversified sourcing earlier in the tariff cycle maintained steadier output levels compared with those that delayed adjustments.
Conclusion
Export tariffs continue to influence material flows and operational decisions across regional woodworking sectors, with measurable effects on inventory practices, species selection, and logistics coordination. Small mills and independent woodworkers respond through incremental changes that align with available resources and local supply conditions, while ongoing data collection from government and academic sources tracks the cumulative impact on production volumes and cost structures.